


A growing market looking for its next growth engines
Carrier Billing remains a significant and growing business in Europe. According to MEF, European consumers acquired around $14 billion worth of goods and services through their Telco accounts in 2025, almost three times the 2019 level. Yet the composition of that growth is changing: just over $5 billion came from DCB/PSMS, compared with almost $9 billion from tariff add-ons and bundling, with the latter growing nearly twice as fast over the past seven years.
DCB also retains a meaningful position in digital commerce: in 2025, more than 10% of digital goods and services revenue in Europe was derived from Carrier Billing. However, merchant-implemented DCB growth is slowing, competition from alternative payment methods is intensifying and margins are under pressure, reinforcing the need for the ecosystem to identify new distribution channels, use cases and revenue models.
Main forces reshaping Carrier Billing
Trust, customer experience and payment performance emerged as central priorities. Fraud prevention, transparency and customer protection are increasingly important to sustainable growth, while improving conversion and payment flows and reducing friction and churn remain core industry objectives.
At the same time, payment behaviours are changing rapidly. Digital wallets more than doubled their share of European consumer spend between 2019 and 2025, while A2A and BNPL also gained ground. Cards and cash combined, meanwhile, fell from 71% of European consumer spend in 2019 to 58% in 2025.
Technology and regulation are also reshaping the market. The shift towards HTTPS is challenging traditional Header Enrichment and increasing the need for future-proof authentication models. Network APIs and digital identity capabilities can help improve security and simplify customer journeys, while standardization and interoperability will be critical to making these capabilities scalable across operators and markets.
Regulatory developments add another dimension. Under the current European framework, unlicensed DCB remains limited to specific categories and transactions are capped at €50 per purchase and €300 per user per month, while the expected evolution towards PSD3 could further reshape licensing requirements and the structure of the ecosystem.
Looking ahead, the discussions pointed towards an evolution of Carrier Billing from payment towards a broader role in distribution and monetization. Among the key takeaways presented by Juniper Research, MNOs were encouraged to leverage RCS to support DCB growth and transform their applications into subscription hubs, creating storefronts where customers can discover and manage multiple digital subscriptions.
That direction is already visible in the market. MEF notes that subscription-hub models can generate direct revenues for operators through resale or revenue sharing while also supporting customer retention. More broadly, subscriptions remain a particularly relevant area for DCB: MEF reports that paid subscribers acquired through DCB are, on average, 20% more likely to be retained than those paying by debit or credit card.
Against this changing backdrop, three next-generation opportunities were particularly central to Digital Virgo’s contribution in Amsterdam.
RCS: turning messaging infrastructure into revenue infrastructure
RCS is moving beyond its role as a richer messaging format towards a communication, distribution and monetization infrastructure.
With native reach, verified identity and rich interactions, RCS can progressively support a much broader customer journey, from acquisition and engagement to service access, payment and customer care. Connecting Carrier Billing directly to these conversational journeys creates opportunities for purchases, subscriptions, ticketing, donations, content access and other transactional use cases.
The challenge is now moving from experimentation to scale. Market coverage, interoperability, brand onboarding, commercially viable pricing and payment integration all need to progress. The industry also needs clear roles and sustainable revenue models across operators, technology platforms, aggregators and brands.
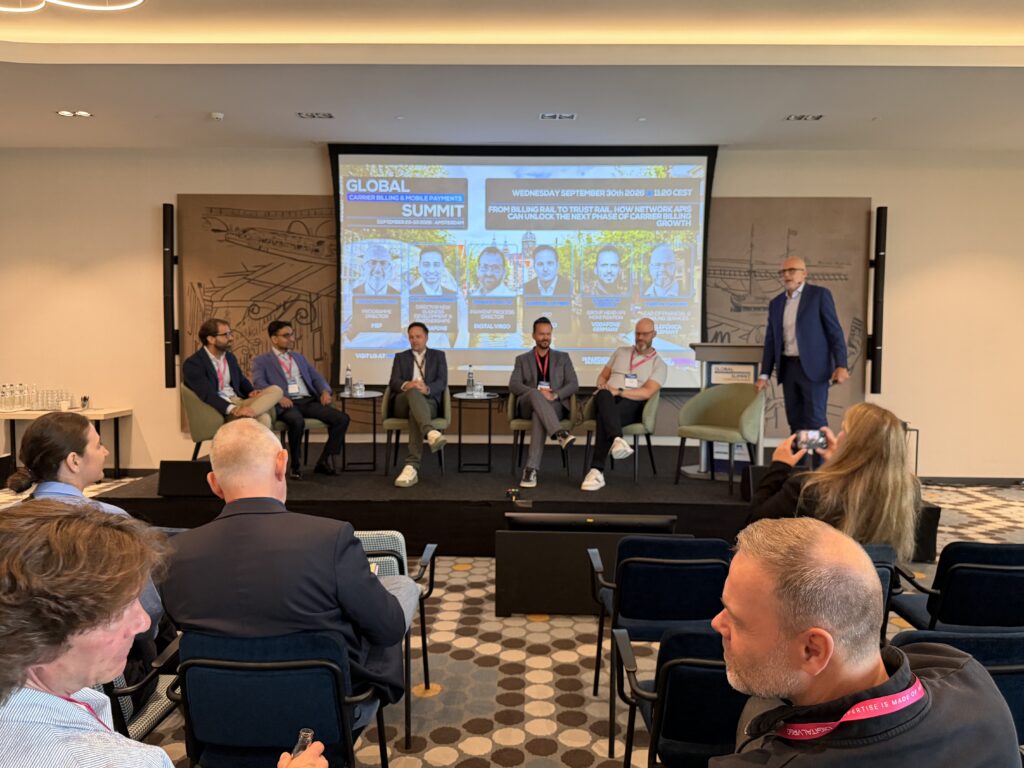
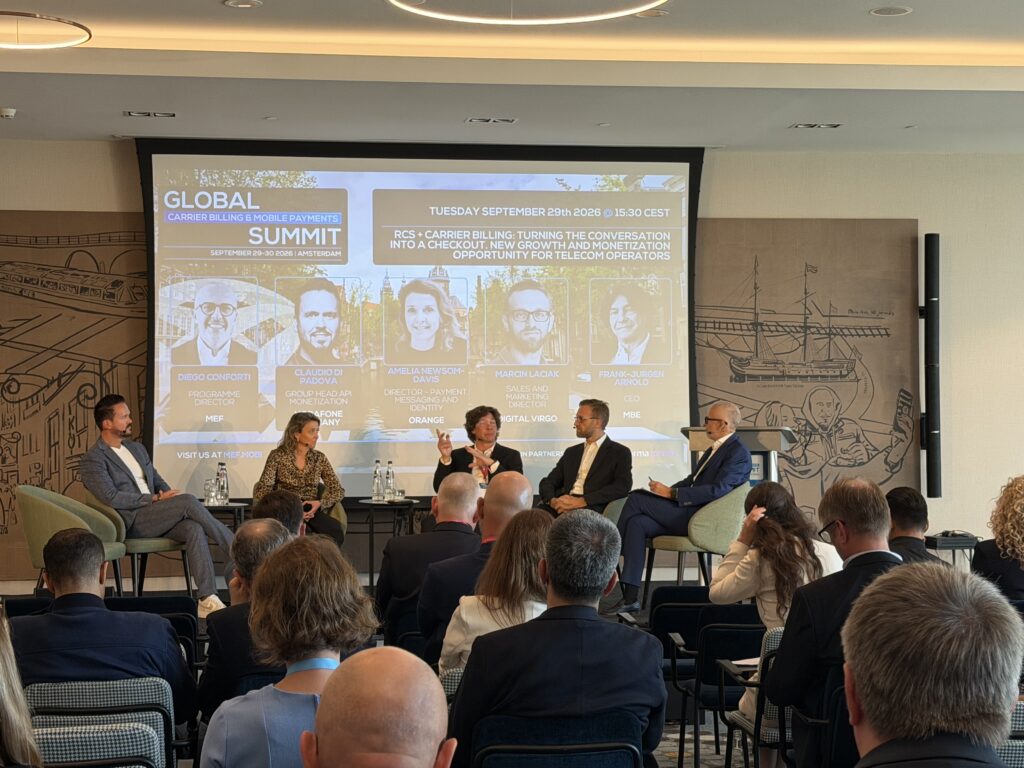
During the dedicated panel, Digital Virgo’s Marcin Laciak joined representatives from Orange, Vodafone Germany, aggregators and the wider ecosystem, to explore this opportunity, highlighting Digital Virgo’s role as a bridge connecting Telco networks, brands and payments, orchestrating end-to-end conversational journeys and turning RCS capabilities into scalable B2B and transactional revenues.
Open Gateway: turning telecom capabilities into business opportunities
Telecom networks hold valuable capabilities beyond connectivity. Through GSMA Open Gateway, capabilities including identity, authentication, security, location and payments can be made accessible to businesses through standardized and interoperable Network APIs.
The opportunity is not simply to expose APIs, but to turn them into concrete business applications. Number Verification, SIM Swap and identity matching, for example, can simplify authentication, strengthen fraud prevention and provide trusted network signals throughout digital customer journeys.
The challenge is adoption: interoperability, standardization, consent, pricing and demonstrable merchant value all need to align before Network APIs can become sustainable revenue streams at scale.
During the From Billing Rail to Trust Rail panel, Digital Virgo’s Ignacio Moltó contributed the merchant and payment perspective alongside industry experts, including Amit Chakrabarti from Vodafone. As a GSMA Open Gateway Channel Partner, Digital Virgo’s role is to connect operators and businesses and combine Network APIs with its expertise in payments, DCB, identity and antifraud, turning telecom capabilities into scalable and monetizable use cases across markets.
The discussion also echoed our recently announced partnership with Vodafone, which expands our established collaboration in Carrier Billing to Network APIs, combining Vodafone’s network capabilities with Digital Virgo’s payment and monetization expertise to develop trusted use cases across identity, authentication and fraud prevention.
DCB as a licensed financial service: towards greater convergence
Another opportunity explored at the Summit was how Carrier Billing could evolve within a broader financial-services ecosystem.
The context differs significantly between markets. In Europe, regulation limits the categories and transaction values accessible to DCB without a payment licence. MEF notes that PSD3 could further reshape the landscape by requiring more aggregators to become licensed payment providers, while licensing could simultaneously open access to broader use cases and higher-value transactions.
In Africa, the starting point is different: Mobile Money has already enabled many telecom operators to build financial infrastructure, licences and deeply established consumer usage.
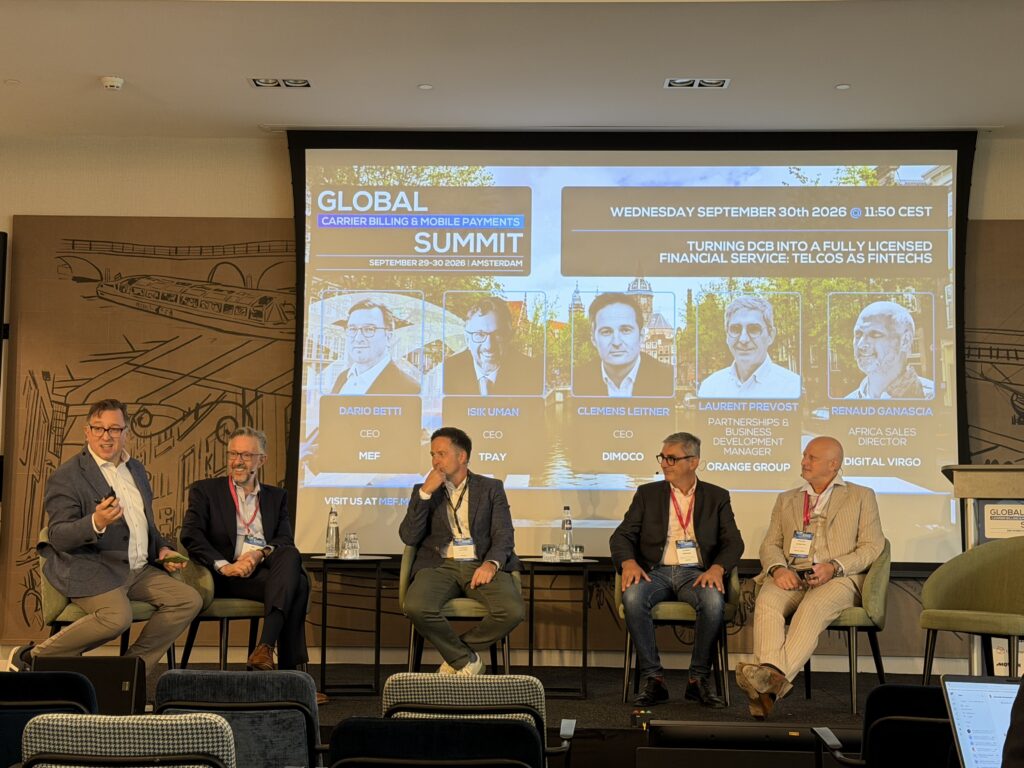
The opportunity discussed during the panel joined by Digital Virgo’s Renaud Ganascia is therefore one of convergence between DCB, Mobile Money and regulated financial services. Rather than adding another isolated payment rail, the objective is to orchestrate multiple capabilities behind one seamless consumer experience and merchant integration, combining the simplicity of DCB, the depth of Mobile Money and the trust of regulated financial services.
From next-generation opportunities to sustainable growth
RCS, Network APIs and new financial-service models address different parts of the Telco value chain, but they point towards the same opportunity: helping telecom operators leverage their infrastructure, capabilities and customer reach to develop new business models and revenue streams beyond connectivity.
The discussions in Amsterdam also made clear that technology alone will not deliver that growth. Consumer trust, interoperability, viable commercial models, regulation, merchant adoption and industry-wide collaboration will determine which innovations successfully move from promising use cases to scalable businesses.
For Digital Virgo, that is where the next phase begins: turning next-generation opportunities into concrete, scalable and sustainable value for telecom operators and the wider digital ecosystem.
Primary source: MEF, Europe’s Carrier Billing Market: Challenges & Opportunities, special report presented at the Summit.